Skip to content
Issuer CIFAS marker

How to Challenge & Remove a Monzo Bank CIFAS Marker

If Monzo closed your account after incoming payments, P2P crypto activity, a social-media job scam, or a disputed transfer, the issue is not simply that the account looked suspicious. Monzo must be able to show clear evidence that your conduct met the CIFAS standard for deliberate dishonesty. We assess where you are in the complaint process, review the Monzo evidence, and recommend the right level of support for your situation.

Free case assessmentProfessional representationFixed 4-stage processCustom pricing outside complaints
Professional Cifas Removal Service
Free Case Assessment
Results in Days
100% Confidential

500+

Markers Challenged

80+

Case Studies

Professional

Cifas Removal Service

Free

Case Assessment

Quick Answer: To challenge a Monzo CIFAS marker, you must submit a formal complaint contesting that Monzo breached CIFAS Principle 4 by failing to prove deliberate dishonesty. Under FCA rule DISP 1.6.2A, Monzo must issue a Final Response Letter within 15 working days before you can escalate to the Financial Ombudsman Service for removal.

Monzo Bank

Can A Monzo Bank CIFAS Marker Be Removed?

Yes. A Monzo Bank CIFAS marker can be removed if the filing cannot be properly justified. The issue is not simply whether Monzo Bank had concerns. The issue is whether the evidence meets the required standard for a CIFAS marker.

We use the Contact Us to complain about:

  • Whether the correct CIFAS category was used
  • Whether Monzo Bank had clear evidence of deliberate dishonesty
  • Whether the marker was based on evidence rather than suspicion
  • Whether innocent explanations, scams, pressure, vulnerability, or third-party involvement were considered
  • Whether the marker is accurate, fair, and lawful under data protection principles
  • Whether the marker should be removed, corrected, or restricted

You do not need to guess what to write. Upload your CIFAS report, Monzo Bank records, and supporting evidence. We prepare the complaint documents needed to dispute the marker properly and guide the next stage if Monzo Bank refuses to remove it.
Monzo Bank

Common Monzo CIFAS Marker Triggers

Social-media job scam or money-mule allegation

The scenario: You were recruited through Telegram, WhatsApp, Facebook, TikTok, or another social platform for a flexible work-from-home, admin, crypto asset, or payment-processing role. You were told to receive money into your Monzo account and forward it on, without understanding that the incoming deposits may have originated from fraud.

The issue: Monzo may treat the payment pattern as evidence of Misuse of Facility, but suspicious movement is not the same as deliberate dishonesty.

P2P crypto or private sale dispute

The scenario: You received funds from a buyer, trader, or exchange counterparty and Monzo later treated those funds as disputed or fraud-linked.

The issue: Monzo must still show that you knew or ought properly to be treated as complicit in the alleged fraud. A transaction pattern alone may be insufficient.

Third-party control, coercion, or vulnerability

The scenario: Someone else controlled the situation, pressured you, used your device, exploited your vulnerability, or persuaded you to act in a way you did not understand.

The issue: The complaint should focus on knowledge, intent, control, vulnerability, and whether Monzo considered innocent explanations before filing.

Need help

Need Help with Your Monzo Bank Cifas Appeal?

You do not need to work out the complaint alone. We assess the marker, the issuer evidence, and what has already happened, then recommend the right level of support for your situation.

1. Contact Us: Tell us what happened, which marker you have, and where you are in the Monzo Bank complaint process.

2. We Assess The Case: We review your CIFAS report, Monzo Bank records, complaint history, and the evidence behind the filing.

3. We Recommend Support: We recommend documents, representation, fast-track support, or custom-priced support if the standard complaint process has already been exhausted.

4. We Prepare And Represent: Where your package includes representation, we handle the complaint process through our fixed 4-stage representation process.

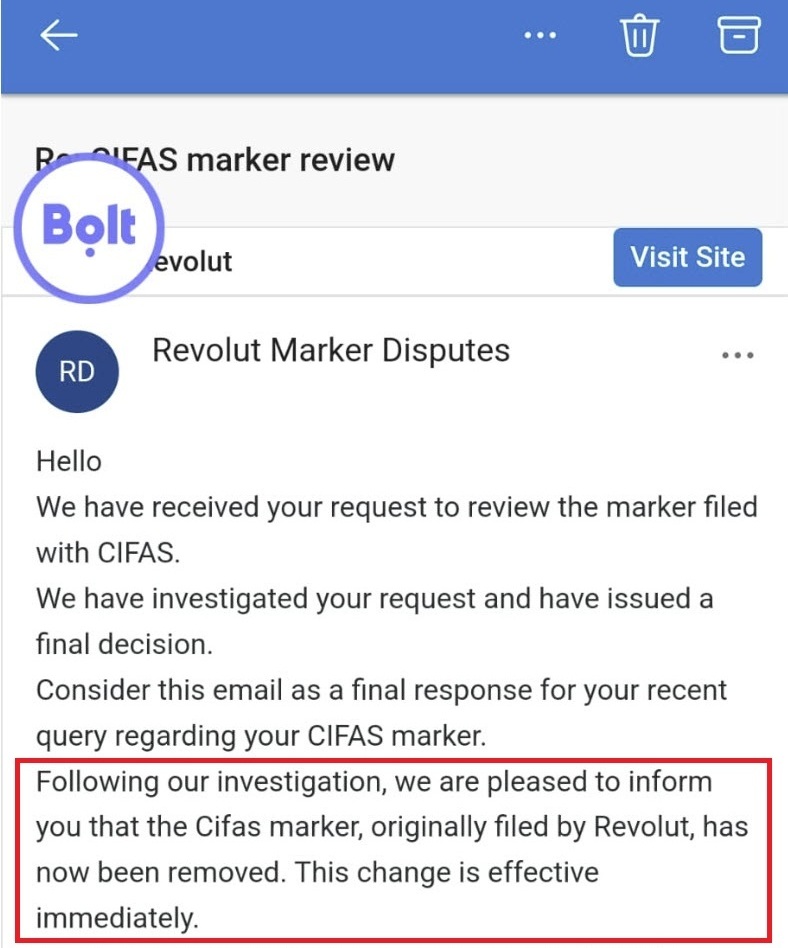
Example CIFAS marker removal result email.

Marker categories

The marker category changes the complaint

A CIFAS marker is not challenged in the abstract. The complaint depends on the category used, the evidence relied on, and whether the issuer can justify that specific filing.

View all markers

Misuse of Facility

MOF

A Misuse of Facility marker usually means an organisation believes your own account or facility was used in suspicious or fraudulent activity, such as receiving or moving suspicious funds.

Read about Misuse of Facility

False Application

FA

False Application usually means an organisation believes false information or documents were used in an application for a financial product or service.

Read about False Application

Facility Takeover

FT

Facility Takeover usually means an account or financial facility was taken over or used by someone without proper authority.

Read about Facility Takeover

Identity Fraud

IF

Identity Fraud usually means identity details were used to obtain a product or service fraudulently, sometimes affecting the victim if the marker is filed incorrectly.

Read about Identity Fraud

Asset Conversion

AC

Asset Conversion usually involves financed or leased goods being sold, retained, or not returned in a way the organisation says was dishonest.

Read about Asset Conversion

False Insurance Claim

FIC

False Insurance Claim usually means an insurer says an insurance claim involved a material falsehood, exaggeration, or false supporting information.

Read about False Insurance Claim

Monzo Bank

Monzo CIFAS Marker Types

  • Misuse of Facility: Used where Monzo alleges an account, payment route, or customer facility was used to receive, move, support, or facilitate fraudulent funds. Learn more
  • Application Fraud: Used where Monzo alleges false, misleading, or incomplete information was provided during account opening, onboarding, or an application process. Learn more
  • Identity Fraud: Used where Monzo alleges identity details were used dishonestly or without authority. Learn more

Monzo Bank

CIFAS Principle 4 - Standard of Proof

Monzo cannot issue a CIFAS marker simply because an account review occurred, an application looked suspicious, a transaction looked unusual, or you violated basic terms and conditions. Under CIFAS Principle 4, Standard of Proof, Monzo must hold a robust file of clear evidence demonstrating:

  1. Reasonable grounds: There must be genuine evidence that a fraud or financial crime was committed or attempted.
  2. Clear, relevant, and rigorous evidence: The evidence must be specific, documented, and capable of scrutiny.
  3. Correct case type: The facts must match the specific CIFAS marker category used by Monzo.
  4. Product decision: There must be a relevant product, account, facility, or service decision connected to the alleged fraud.

The question is not whether Monzo had a reason to be suspicious. It is whether Monzo can evidence deliberate dishonesty or knowing involvement to the standard required for a fraud-risk filing.

Monzo Bank

Monzo CIFAS Marker Removal Pricing

Prepared documents

Documents Package

We prepare the complaint documents and evidence summary for your current complaint stage. You remain responsible for handling parts of the complaint process.

£500one-off
Get assessed
Most popular

Representation Package

We handle the complaint process for you using our fixed 4-stage professional representation process.

£1,000one-off
Get assessed
Urgent support

Fast Track Support

Priority support for urgent cases, including full complaint process support and court documents where needed. Anything outside the standard complaint process is assessed and priced separately.

£1,500one-off
Get assessed

If your case is already outside the standard complaint process, for example after a Financial Ombudsman rejection or where court proceedings are required, we assess the position first and confirm any custom pricing before work starts.

Cifas Service Comparison

Feature / Support Level1. Documents Package2. Representation Package3. Fast Track Support
Best forClients who need prepared complaint documentsClients who want us to handle the complaint processUrgent cases needing priority complaint support
SupportComplaint documents and evidence summaryRepresentation through our fixed 4-stage processPriority support plus court documents where needed
Pricing£500£1,000£1,500

Assess your Cifas Marker

  • Take our 2-Minute CIFAS Assessment to see if your Monzo marker can be legally challenged.
  • Fixed-Fee Document Preparation.
  • Case Merits Assessment.

Subscriptions can be cancelled at any time to prevent future billing. Fixed-fee packages are non-refundable once work has commenced.

Non-regulated legal support service. Documents prepared for Litigants in Person.

You will be billed £149.99 every month until you cancel.

Monzo Bank

The Financial Ombudsman's Warning on Generic AI Submissions

The Financial Ombudsman Service has warned consumers about the risks of using AI without proper checks in complaint submissions. Marc Harris, Chief Operating Officer at the Financial Ombudsman Service, stated that "excessive or uncritical use of generative AI can lead to" hallucinations, fabricated laws, misquoted regulations, invented past decisions, and erroneous service complaints.

Our AI Agents are not a generic chatbot wrapper. They are used inside a supervised document-preparation workflow with case data, complaint structure, evidence review, and human support where required.

Monzo Bank

Managing Banking With CIFAS Marker

While your CIFAS marker is actively being challenged, traditional automated banking applications may result in quick rejections.

  • Avoid repeated mainstream applications while the marker is live.
  • Consider basic bank account options where no overdraft or credit facility is required.
  • Keep evidence of account closures, refusals, and employment or mortgage impact.
  • Do not send emotional explanations to banks without first understanding the CIFAS record and the issuer evidence.

Monzo Bank

Monzo CIFAS Marker History

Monzo case study: marker removed in 10 days

  • Issue: Monzo filed a Misuse of Facility marker after a Telegram job-scam pattern.
  • Key point: The complaint focused on whether Monzo had evidence of knowledge and dishonest intent.
  • Outcome: Marker removed after a structured complaint challenged the evidence and victim context.
  • Read more: Monzo Misuse of Facility marker removed in 10 days

FOS case: Monzo, DRN-4936783, marker removed

  • Issue: Monzo relied on suspicious account activity.
  • Key point: The Ombudsman looked at whether Monzo had enough evidence to justify the marker.
  • Read more: Read DRN-4936783

Legal Disclaimer

The information provided in this guide is for educational and informational purposes only. It does not constitute formal legal or financial advice. Success rates for CIFAS marker removals depend entirely on individual case evidence, and a successful deletion outcome can never be 100% guaranteed.

Specialist CIFAS marker removal firm

Challenge Your Monzo Bank CIFAS Marker

Professionally drafted complaint documents built around your marker, issuer, and evidence. We manage the process at every stage where your package includes representation.

WhatsApp Us